Security Bank sees new role for branches
In digital banking era
MANILA, Philippines — When Victor Lee took over as president and chief executive officer of Security Bank Corp. in January, one thing about Philippine banking puzzled him: why were banks still opening branches when more customers were increasingly doing transactions through their phones?
Eight months into the job, Lee said he has come to see the branch less as a place for routine transactions and more as a venue for advice, relationships and more consequential financial decisions.
“I joined the bank in January and I kept scratching my head, why are we still opening branches?” Lee said during a recent media roundtable. “Banks still open branches and I think that’s something very unique in this market.”
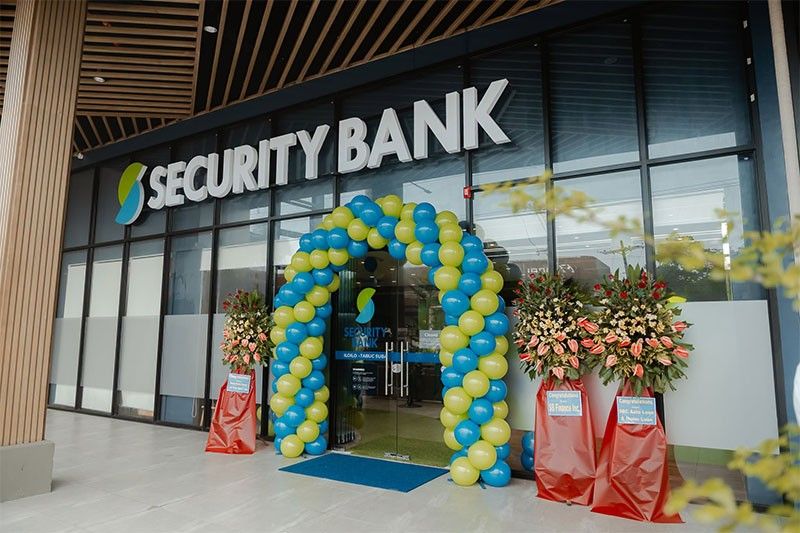
Security Bank expects to end the year with around 400 branches nationwide, up from 290 in 2016, even as it continues to invest heavily in digital banking for both retail and business customers.
For Lee, the continued relevance of physical branches does not necessarily contradict the shift toward digital banking.
“Retail transactions over the counter at the branches have reduced substantially,” he said. “But, you know, customers still love the face to face relationship, that homeliness we bring them in.”
Lee said branches remain important for financial advisory and customer engagement, even as simple transactions migrate online.
He added that Security Bank might no longer expand its physical network as quickly as it did in recent years, with close to 400 branches already giving the lender broad coverage nationwide.

The bank’s strategy reflects a broader shift in how lenders think about digital banking. Instead of simply replacing physical channels, Security Bank is trying to determine which interactions are better handled online and which still benefit from human advice.
Its retail digital platform currently has 1.71 million customers, about 65 percent of which are active users. The app allows clients to open accounts, transfer funds, save, invest and manage card security.
But Security Bank chief financial officer John David Yap said the objective goes beyond simply migrating customers to digital channels.
“Scale alone is not the objective. The real opportunity for us is to turn a frequent digital interaction into a deeper financial relationship,” Yap said. “An app completes a transaction. A great digital bank earns the next financial decision.”
The same approach is shaping Security Bank’s business banking strategy.
Around 40 percent of its business clients currently use the bank’s cash management services, which allow companies to manage collections, payments and other day-to-day financial transactions.
According to Yap, clients using these services maintain deposit balances that are around 150 percent higher than those that do not. Customers using more advanced cash management products show a further 32-percent improvement in deposit balances.
For banks, that matters because transaction banking can deepen a customer relationship while also bringing in more operating deposits. These are funds that naturally flow through a company’s accounts as it collects from customers, pays suppliers and manages payroll.
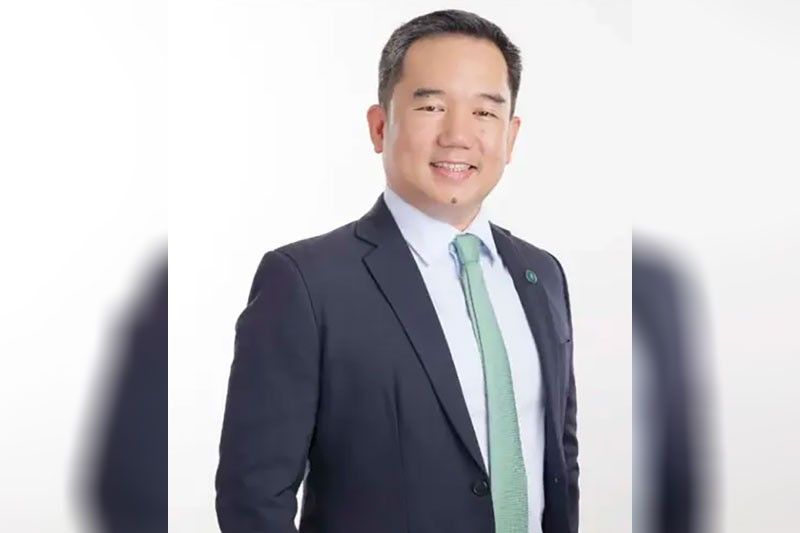
“This is not simply a channel migration. When the bank becomes part of the client’s daily operating activity, the relationship changes,” Yap said. “Deposit deepens, product use broadens.”
Security Bank received approval from the Bangko Sentral ng Pilipinas in June to launch an upgraded digital banking platform for corporate and micro, small and medium enterprise clients. The bank has started migrating customers to the platform and is targeting completion by year-end.
The lender also sees a continuing role for human interaction in wealth management, one of three priority businesses under its three-year strategy alongside entrepreneurial banking and corporate and institutional banking.
Lee said financial advice is becoming more personal as more Filipino households accumulate wealth and face increasingly complex investment and succession decisions.
For wealth clients, Security Bank wants digital channels to handle simple and recurring transactions while relationship managers step in when customers face bigger financial decisions.
“A routine transaction should take seconds. A consequential decision should come with trusted advice,” Lee said. “The winning wealth model will not be digital or human. It will know precisely when the customer needs each one.”
The same thinking applies to entrepreneurs.


- Latest
- Trending