CTA affirms acquittal of Ressa, Rappler in tax cases
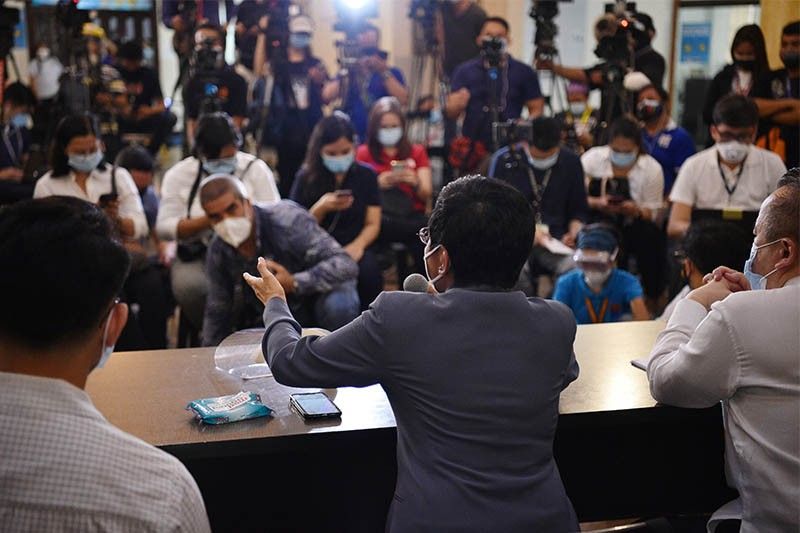
MANILA, Philippines — The Court of Tax Appeals (CTA) has upheld the acquittal of Rappler CEO Maria Ressa and Rappler Holdings Corp. (RHC) in multiple tax-related cases, reaffirming that the media company did not violate the National Internal Revenue Code (NIRC).
In a decision promulgated on Feb. 21, 2025, the CTA en banc denied the petitions for review and certiorari challenging its First Division's 2023 ruling, which found Ressa and RHC not guilty of three counts of failure to supply correct information and one count of tax evasion, allegedly involving P141 million in taxes.
The Bureau of Internal Revenue (BIR), represented by the Office of the Solicitor General, had filed a petition questioning the ruling after the Fiirst Division junked its motion for reconsideration.
The appellate tax court reaffirmed that RHC's issuance of Philippine Depositary Receipts (PDRs) was not a taxable transaction, as it did not constitute a regular purchase and resale of securities. Instead, the court found that RHC issued PDRs solely to raise capital for its subsidiary, Rappler Inc.
"Evidence on record shows that RHC was not habitually or regularly engaged in the purchase and resale of securities, as the issuance of the PDRs was done pursuant to a legitimate business purpose," the ruling read.
Since no gain or profit was made from the transaction, and it was not classified as a sale of shares, the court ruled that RHC was not required to pay income tax and value-added tax (VAT) on the PDR transactions.
The court also pointed out that the PDRs were issued by RHC itself and were not purchased from another party and then resold.
"Finally, the PDRs were issued by RHC and were not purchased from Rappler Inc. and resold to NBM Rappler L.P. and Omidyar Network; thus, its subscription is not considered dealing in securities as defined under the NIRC of 1997, as amended, the Securities Regulation Code (SRC), and Revenue Regulations No. 6-2008," the CTA said.
The CTA en banc also rejected the BIR's arguments, stating that they were mere rehashes of previous claims that had already been extensively addressed by the Fiirst Division.
"Accordingly, the court en banc finds no reason to modify or reverse the disposition in the assailed decision and assailed resolution," read the decision penned by Associate Justice Corazon Ferrer-Flores.
The en banc further stressed that there was no grave abuse of discretion on the part of the First Division in rendering its earlier decision.
"Here, petitioner was able to present documentary and testimonial evidence, which the court in division appreciated and evaluated during trial," the CTA said.
Background of the case
The BIR initially filed complaints against Ressa and RHC on March 8, 2018, alleging that the company had outstanding tax liabilities arising from trading income earned through the issuance of PDRs to foreign investors. The agency accused RHC of deliberately avoiding income and VAT payments in 2015 by allegedly acting as a securities dealer.
However, the CTA has now ruled twice in favor of Ressa and Rappler, stating that the transactions in question were lawful and did not warrant tax evasion charges.




- Latest
- Trending