

Government microloans draw 650,000 borrowers
CEBU, Philippines — More than 650,000 Filipino workers have tapped government-backed microloan programs in less than two years, underscoring strong demand for fast, relatively low-cost credit for everything from medical bills and tuition to household emergencies and small-business needs.
The Social Security System (SSS) and Government Service Insurance System (GSIS) have together disbursed more than P31.7 billion through their digital microloan programmes, as policymakers seek to channel workers away from informal lenders that can charge substantially higher rates.
The figures highlight a persistent gap in the Philippines’ credit market: workers may need only a few thousand pesos to bridge a short-term cash crunch, but traditional lending can be poorly suited to such small and urgent borrowing needs.
The government is seeking to fill that gap with SSS LoanLite for private-sector workers and GSIS Ginhawa Go for government employees. Both programs offer relatively small loans through digital channels, with repayment structured around the borrower’s employment or social insurance relationship.
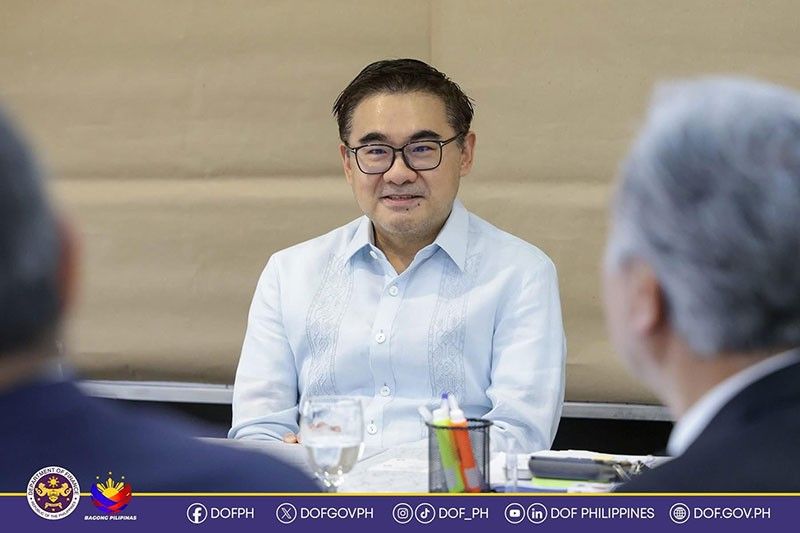
Finance Secretary Frederick Go has backed the initiatives as a way of meeting workers’ immediate financing needs without adding unnecessarily to their debt burden. The programmes are also intended to provide an alternative to informal “5-6” lending, where borrowing costs can be significantly higher.
The response has been particularly rapid at SSS.
UnionDigital Bank, the first participating financial institution for SSS LoanLite, disbursed P2.08 billion to about 170,000 members in just 41 days between Aug. 10 and Sept. 28, 2026.
GSIS Ginhawa Go has operated on a much larger cumulative scale. From Oct. 24, 2024 to Sept. 28, 2026, the program, including its Lite offering, released P29.67 billion to more than 480,000 government employees.
Taken together, the figures point to a sizeable market for short-term borrowing that can be accessed quickly and repaid in manageable amounts.
SSS LoanLite
Qualified SSS members can borrow between P1,000 and P20,000, depending on their average Monthly Salary Credit. The interest rate is 8 percent a year, equivalent to about 0.67 percent a month, with repayment periods of 15, 30, 60 or 90 days.
A P10,000 loan would accrue about P67 in interest over one month at the stated annual rate, before any applicable fees and depending on the repayment terms.
LoanLite can be accessed without employer certification, reducing one administrative hurdle for qualified members.
UnionDigital Bank currently offers the product through its digital channels. RCBC has also joined the program and is expected to offer SSS LoanLite through its DiskarTech app by October.
GSIS Ginhawa Go
Ginhawa Go allows eligible government employees to borrow between P1,000 and P50,000.
Loans of up to P4,000 can be repaid over 30, 60 or 90 days. Borrowings from P5,000 to P50,000 can be repaid over three, six, 12, 18 or 24 months.
Interest rates range from 6 percent to 7 percent a year, calculated in advance. The applicable rate and loan amount depend on factors including the member’s category and length of paid premium contributions.
Members with at least three years of paid premiums qualify for the 6 percent annual rate. A P10,000 loan repaid over 24 months would carry P1,200 in total interest under the stated calculation.
Applications are made through the GSIS Touch mobile app, with requests subsequently routed to the authorized officer of the member’s government agency for approval.
Repayment is made through mandatory payroll deductions, while SSS LoanLite payments are collected through the participating financial institution’s payment channels.
Competing on convenience
The programs are effectively competing with informal lenders on one of their strongest selling points: speed.
For workers facing an unexpected expense, the ability to borrow a relatively small amount through a mobile phone can matter as much as the headline interest rate. The government-backed schemes are designed to combine that convenience with lower stated borrowing costs and repayment mechanisms tied to formal employment.
The rapid take-up of LoanLite suggests that demand for such products is not marginal. It also highlights the extent to which workers continue to need accessible credit for expenses that may be too small, too urgent or too short-term for conventional bank financing.
Members are advised to use only official application channels and to review the applicable interest rate, fees, repayment schedule and other terms before accepting a loan.




- Latest